Business
‘I invested In A Ponzi Scheme’: Nigerians Fall Victim To Crypto Scams

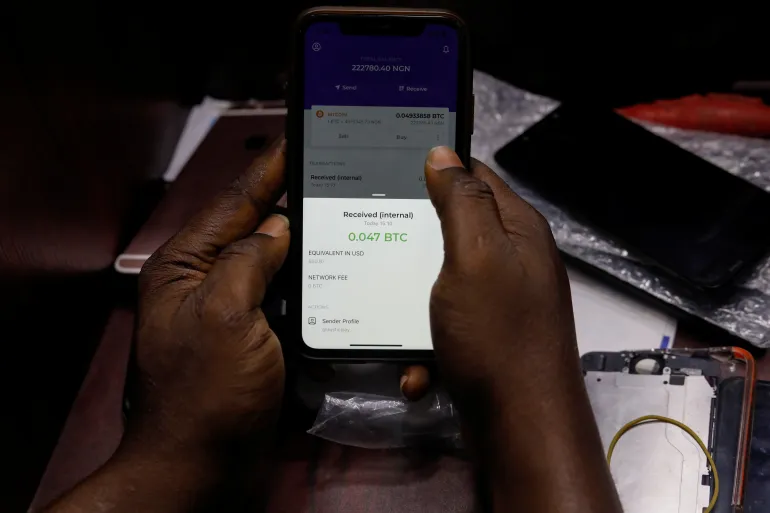
Experts say financial illiteracy, lax regulations, greed and economic hardship make people susceptible to scam companies.
Lagos, Nigeria — Mandela Fadahunsi, who works at a technical training school in Ikeja in Nigeria’s Lagos, never believed he could fall victim to a Ponzi scheme.
On April 6, the 26-year-old was starting his day when a WhatsApp notification lit up his phone screen. Someone on the group chat for investors of the cryptocurrency investment platform, Crypto Bridge Exchange (CBEX), had tried and failed to withdraw some funds, so they wanted to confirm if it was a general issue. Fadahunsi quickly logged on to his digital wallet and tried to withdraw 500 USDT, a cryptocurrency that stands for United States Dollar Tether, or simply Tether.
But 24 hours later, a process that should have taken just 10 minutes was yet to complete. He knew then that something had gone wrong. He started to panic, but half-hoped it was just a glitch or a minor system error.
“They [CBEX administrators] said it was as a result of the excessive volume of people trying to withdraw, and that all withdrawals have been placed on hold until 15th of April,” Fadahunsi told Al Jazeera.
On the 15th, he and fellow investors waited but heard nothing. On subsequent days, the administrators gave more excuses until the site stopped working altogether, and everyone’s money disappeared without a trace. That is when he realised he had been scammed and might never be able to recover the 4,596 USDT stablecoin in his wallet.
While Fadahunsi tallied his losses, the issue went viral on social media platforms.
Many more Nigerians shared their stories of loss, while others mocked them for losing their money to scammers. Some members of the public, filled with rage, attacked and ransacked CBEX offices in Ibadan and Lagos.
CBEX launched operations in Nigeria in July 2024, claiming to be able to generate immense trading profits using generative artificial intelligence. By January, it had gained serious popularity through referrals and smart advertising.
Fadahunsi and thousands of other people invested with the hope of making a maximum profit – the scheme promised up to 100 percent return on investment after a 40- to 45-day maturation period. At the start, the scheme did pay out, and the testimonies of successful initial investors attracted more people to sign up.
But after nine months of operation, the music stopped as the platform made away with an estimated 1.3 trillion naira ($840m), according to the official Nigerian Financial Intelligence Unit (NFIU). It left investors stunned.
Nigeria’s anticorruption agency, the Economic and Financial Crimes Commission (EFCC), has since labelled CBEX a Ponzi scheme. Experts say the organisers of such scams usually promise to invest people’s money in something that generates high returns, but in reality, it is investment fraud that pays existing investors with funds collected from new ones. Once a large number of people cash out, and new investors into the scheme dry up, it collapses.
Ponzi schemes, including CBEX, are usually not backed by any discernible economic activity, experts say. According to Ikemesit Effiong, from the Lagos-based socioeconomic advisory firm, SBM Intelligence, most times these businesses do not have anything to sell and have no recognisable business models. Even the agriculture-based ones claim to have products that investigators are unable to track. They also largely rely on existing investors to bring in new investors who serve as their downlink in the pyramid scheme.
Experts say that in Nigeria, widespread financial illiteracy, lax regulations, greed, economic hardship and peer pressure make investors susceptible to the machinations of Ponzi organisations that combine aggressive advertising, word-of-mouth campaigns charged by incentives, and initial high returns.
But at the end, the schemes leave victims – many of whom invest their savings, business capital, and borrowed money – unable to do anything but watch their hard-earned money disappear.
‘Make some gains’
Fadahunsi first heard about the CBEX scheme from colleagues at the start of the year. Initially, he was hesitant. But a few days later, his neighbour also mentioned the platform. Recognising that his close associates were participating, and not wanting to miss out, he decided to invest.
“I also thought the money was just sitting in my account, and it could be somewhere where I can make some gains on my money,” he explained.
In early February, he dipped into his rent savings and withdrew the entire 800,000 naira ($517). With that, he bought 500 USDT from the crypto exchange platform Buybit, receiving the coin in his digital CBEX wallet.
Four times a day on the CBEX platform, administrators dropped a code, which they call a “signal”. Investors were required to copy and paste the code into a section of their portal within the hour. CBEX said AI would then use that to make a trade, basically to buy and sell or change positions in such a way that it made a profit from price fluctuations on the investors’ behalf. Each time Fadahunsi pasted in the code, he would get 4.7 to 5 USDT as a profit, all of which accumulated towards his returns.
“So the more you do it, the more the percentage increases. In a month, I got double of 500 USDT,” he said, adding that there were also bonuses for things like referrals.
In March, users said CBEX made an adjustment where they no longer input the signal. Instead, investors just had to turn on an “AI hosting” option at the start of the day. But some investors say this was likely just a ploy to keep them going, to convince them they were still making a profit before everything crashed in April.
While some investors withdrew their returns, by the time CBEX crashed, Fadahunsi had not withdrawn any money. He had wanted to maximise the investment opportunity, to leave the funds to grow for five to six months before using them to buy a plot of land to build his future home. Now, that dream is dead.
“It is very hard, but thank God that my landlord is actually understanding,” he said.
“I am not proud of opening my mouth [to say] that I actually invested in a Ponzi scheme,” he lamented. “If I wasn’t greedy, I should have been able to withdraw two to three times on the platform, and it would have been successful.”
The USDT that CBEX invested in is a stablecoin pegged to the US dollar [File: Afolabi Sotunde/Reuters]
A history of Ponzi schemes
Even before CBEX, Ponzi schemes were not new in Nigeria.
In March, Nigeria’s anticorruption agency published a list of 58 Ponzi schemes presently operating in the country, and advised the public to “be vigilant and proactive”. This highlights the widespread presence of fraudulent entities masquerading as legitimate businesses in the country: in 23 years, Nigerians lost 911 billion naira ($589m) to Ponzi-related scams, the National Deposit Insurance Corporation (NDIC), which protects the country’s banking system, said in 2022.
Often, Ponzi schemes are able to operate by leveraging grey areas, such as obtaining an irrelevant certification that exaggerates their significance or legitimacy.
CBEX, for instance, obtained the EFCC’s anti-money laundering certificate through the corporate identity of ST Technologies International Ltd, and paraded it as a kind of clearance for conducting business.
However, the NFIU said CBEX was never granted a registration by the Securities and Exchange Commission (SEC) to operate as a Digital Assets Exchange, solicit investments from the public or perform any other function within the Nigerian capital market.
Legitimate businesses can be verified by checking the SEC website. However, experts say the vast majority of those who invest in shady schemes seem unaware or uneducated about this – 38 percent of Nigerians are financially illiterate, according to a 2023 central bank report.
At the same time, other victims may be willing participants, at least at first.
Joachim MacEbong, a senior analyst at Stears, a Lagos-based financial advisory firm, said while some victims are unwitting, others intentionally walk into Ponzi schemes hoping to make a quick profit before it crashes.
“There are those who know it is a scam, but they always feel they could cash out before everybody else. And so they would make that calculation, and it is largely because of the situation in the country; there is a lot of hardship. This kind of hardship increases the people’s desire to take risks and gamble with their very important funds,” he explained.
Nigeria’s economy has been on a downward spiral for decades, and is worse now that the country is going through its toughest economic downturn in about 30 years. Food prices have soared, and basic amenities are becoming inaccessible as the inflation rate sits at 23.71 percent. Against this backdrop, some see Ponzi schemes as a fast way to break out of the vicious cycle of poverty.
Like the proverbial early bird, early investors benefitted from the CBEX scheme, multiplying their returns for several months. Although social media is agog with complaints and bitter disappointment, some people said they had been able to make major purchases such as land and cars from their investment.
“The time scale at which you enter the investment will determine whether it will be a good investment or you will be a victim,” said Effiong of SBM Intelligence, but he added that many new investors are unaware of this catch.
‘We had a lot of plans’
Waris Oyedele is one of the people who invested their savings in CBEX because of worsening financial hardship in the country.
When he realised that the investment had crashed, he wept.
The 25-year-old comes from a low-income family. He graduated from Obafemi Awolowo University last year, but when he could not get a job, he started working as a shoemaker.
In January, he invested his savings of 800,000 naira (500 USDT); by March he had made 1,200 USDT.
He gave the returns to his younger brother to reinvest to help him pay for his future university studies, and in doing so, help ease their father’s financial burden.
“I felt bad [when we lost the money] because we had a lot of plans on it,” Oyedele said.
“I had a plan of buying a computer and going into UI/UX. Now it has gone.”
He is deeply affected by the situation and has reduced the way he spends his tiny income as he tries to rebuild his savings for future use and to support his brother.
Ponzi schemes play on psychology and human instincts by making it seem as though easy money is within reach, Effiong of SBM said.
All investments involve some form of greed, Effiong explained, and the promise of ending up with a higher return is one of the most elementary forms of human motivation: we all want more and as quickly as possible.
“What [a Ponzi scheme] does is that it also unlocks the deep-seated psychological bend for human beings to join groups – the obvious fear of missing out,” he said. “It also thrives on really aggressive marketing – all of that is to prey on the psychology of potential investors to not slow down.”
Agile tactics
Over the years, Ponzi schemes have employed several techniques to appeal to people, even going the extra mile to try and build public trust and goodwill. CBEX, for example, organised a sports competition and ran scholarships for schoolchildren to throw off suspicion, experts said.
In Nigeria, schemes rely heavily on existing investors who are incentivised to introduce new investors. They also engage in aggressive marketing using local and social media, sometimes involving radio, influencers and celebrity endorsements. Afrobeats stars Davido and Rema are some of the most popular celebrities to have unknowingly endorsed and made promo videos for Ponzi schemes in the past.
Ponzi schemes are also becoming increasingly sophisticated and dynamic as they leverage the latest technologies and digital tools, experts say.
“Many of them have apps with wonderful user experiences, which lend an air of credibility to their enterprise. Many of these scammers go to great lengths to design their products in such a way that they look and appear credible,” Effiong said.
MacEbong from Stears agreed, saying fake news and misinformation campaigns will become supercharged using AI tools, making it easier to hoodwink unsuspecting victims.
“There are numerous examples of generative AI being used to fool people who are even well informed and more savvy. When you turn these various tools against people with much lower exposure and information, they are practically defenceless,” MacEbong explained.
Regulators such as the SEC must become more proactive and come up with agile tactics to rein in Ponzi schemes and protect the public from illegitimate enterprises and shut them down before they cause harm, experts told Al Jazeera.
Businesses must be registered and thoroughly vetted because Ponzi schemes have been erroneously certified in the past, Effiong emphasised.
“There has to be a lot of financial education. Financial literacy is critical, which goes beyond how to make money, but [also] to educate the public on the tell-tale signs of Ponzi schemes. The responsibility also lies with the general public to educate themselves. If it sounds too good to be true, chances are it is too good to be true,” he said.
On May 26, EFCC said it had recovered a portion of the money stolen by CBEX and arrested two individuals promoting it. Al Jazeera tried to contact CBEX for comment through its website and publicly available phone numbers, but all were unavailable or out of service.
Meanwhile, many investors like Fadahunsi have lost hope and believe that the money they invested is all gone.
“Whatsoever the authorities retrieve, I am sure that nothing is going to come to me; I moved on already,” he said. “That is a very tough lesson for me. [Now,] I would rather keep my money in my account and spend it till the last dime.”
Aljazeera.com
The Nigerian National Petroleum Company Limited (NNPCL) has reduced the pump price of petrol by N5 per litre at its retail outlets in Lagos from N1,360 to N1,355.
Motorists in Lagos and Rivers now pay N1,355 per litre, making them the cheapest locations on NNPC’s updated price list. Abuja buyers are paying N1,370 per litre under the new arrangement.
NNPC petrol prices across Nigeria
Yobe has the highest petrol price at N1,435 per litre, followed by Niger State at N1,433.
Borno, Gombe, Nasarawa and Sokoto are all priced at N1,430 per litre, placing them among the states with the highest fuel prices.
Several south-western states fall within the lower price range. Ogun and Oyo both sit at N1,367, while Osun is priced at N1,358.
Akwa Ibom is at N1,360, just above the Lagos and Rivers rate.
In the south-east, Anambra, Enugu and Imo are each priced at N1,372, with Ebonyi slightly higher at N1,375. Abia is priced at N1,370, the same as Abuja.
Further north, Kaduna is at N1,400, Zamfara at N1,414, while Adamawa, Jigawa, Kebbi, Plateau and Taraba are all priced at N1,420. Bauchi and Kano share a rate of N1,385, while Benue is at N1,410.
In the South-South, Delta is priced at N1,379, Bayelsa and Edo at N1,380, and Cross River at N1,390. Kwara is at N1,375, while Kogi is priced at N1,390. The full breakdown of the new NNPC petrol prices per litre is as follows:
Lagos: N1,355 Rivers: N1,355 Akwa Ibom: N1,360 Osun: N1,358 Ogun: N1,367 Oyo: N1,367 Abia: N1,370 Abuja: N1,370 Anambra: N1,372 Enugu: N1,372 Imo: N1,372 Ebonyi: N1,375 Kwara: N1,375 Ekiti: N1,377 Ondo: N1,377 Delta: N1,379 Bayelsa: N1,380 Edo: N1,380 Bauchi: N1,385 Kano: N1,385 Cross River: N1,390; Kogi: N1,390 Kaduna: N1,400 Benue: N1,410 Zamfara: N1,414 Adamawa: N1,420 Jigawa: N1,420 Kebbi: N1,420 Plateau: N1,420 Taraba: N1,420 Borno: N1,430 Gombe: N1,430 Nasarawa: N1,430 Sokoto: N1,430 Niger: N1,433 Yobe: N1,435
Business
From Kabiru to Khalifa: How Abdul Samad Rabiu is Quietly Positioning his Son in the Corridors of Business and Power
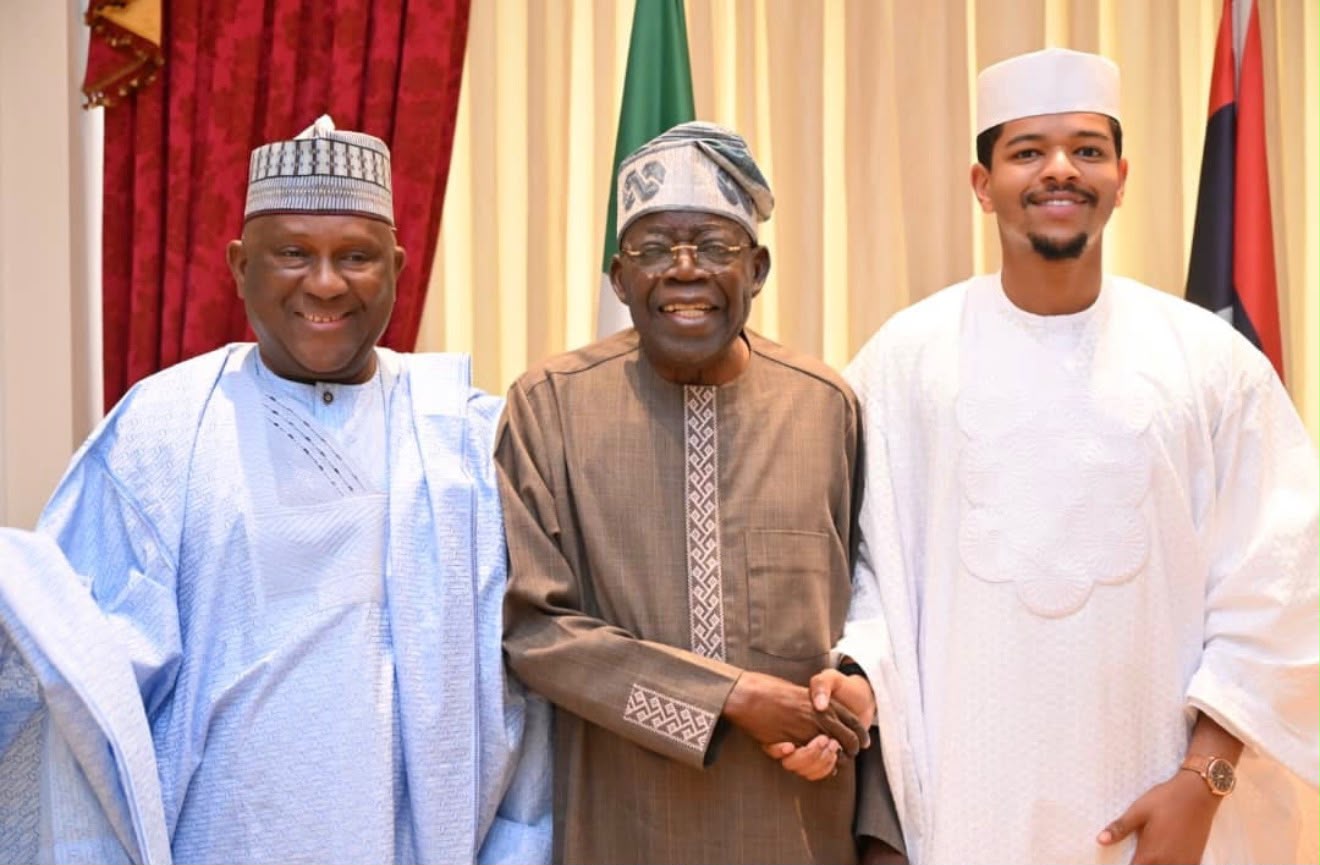
Once, his younger brother Kabiru was one of the familiar family figures around the BUA empire. Now another generation is moving steadily into view as Abdul Samad Rabiu brings his son, Khalifa, closer to the business, relationships and rarefied circles surrounding one of Africa’s largest industrial fortunes.
On Friday, October 2, 2026, when Abdul Samad Rabiu went calling on President Bola Ahmed Tinubu at his Ikoyi residence in Lagos, he did not go alone. Beside the billionaire industrialist was his son, Isyaku Abdulsamad “Khalifa” Rabiu, the young BUA executive whose presence increasingly seems to accompany his father into rooms where business, government and influence converge. Rabiu said the visit afforded an opportunity to reflect on Nigeria’s journey and its future, while other reports confirmed that the BUA chairman was among several prominent business and political figures received by the President that day.
On the surface, there was nothing extraordinary about it. Wealthy fathers travel with their sons, introduce them to friends and take them to important engagements every day. Yet, when the father is Abdul Samad Rabiu, founder of an industrial empire painstakingly assembled over decades, and the son has recently moved into a strategic executive position within that empire, the optics acquire a different texture. A photograph becomes more than a photograph; a handshake begins to look like an introduction, and what appears to be a simple father-and-son outing starts to resemble that ancient ritual through which successful men gradually acquaint the next generation with the world they may one day have to navigate without them.
For those who have watched Abdul Samad through the years, the changing silhouette around him is difficult to miss. There was a time when his younger brother, Kabiru Rabiu, represented one of the most prominent family presences within the BUA establishment, rising through the group’s operations and eventually becoming Group Executive Director, while also serving as a non-executive director of BUA Foods and BUA Cement. He remains firmly embedded in the conglomerate, with more than two decades of experience across edible oils, cement and infrastructure.
Kabiru belongs to Abdul Samad’s generation, however, and that distinction matters because every family empire, no matter how vast or professionally managed, eventually encounters the question that money alone cannot answer: what happens when the generation that built it begins to make room for the generation that must preserve it?
It is within that quiet, complicated passage that Khalifa is increasingly becoming interesting.
His emergence has not arrived with trumpets, ceremonial titles or the public unveiling of a successor. Abdul Samad has not declared him heir to BUA, and nothing in the public record justifies such a conclusion. What has become visible instead is something subtler and perhaps more meaningful: a gradual accumulation of responsibility, exposure and proximity, the three ingredients through which the children of powerful business families are often introduced to the burden behind the privilege.
Khalifa is no longer merely the billionaire’s son appearing occasionally beside his father. On January 29, 2026, BUA Foods appointed him Chief Officer, Global Procurement and Strategic Operations, giving him responsibility for the company’s end-to-end global procurement function and strategic operational initiatives. Before that appointment, he served as Director for Special Operations at BUA Group, where his work included transformation projects, supplier relationships, wheat sourcing, animal-feed production, the commercial reintroduction of BUA rice and other operational initiatives.
There is something instructive about where he has been placed. For the son of one of Africa’s wealthiest industrialists, a grand office and ornamental designation would have been easy enough to manufacture, the sort of corporate embroidery with which family businesses sometimes decorate heirs who have yet to acquire the scars of enterprise. Khalifa, however, has been taken closer to procurement, supply chains and operations, into the less glamorous entrails of an industrial organisation where fortunes are not discussed in abstract terms but depend on the relentless movement of wheat, sugar, machinery, ships, suppliers, currencies, warehouses and markets.
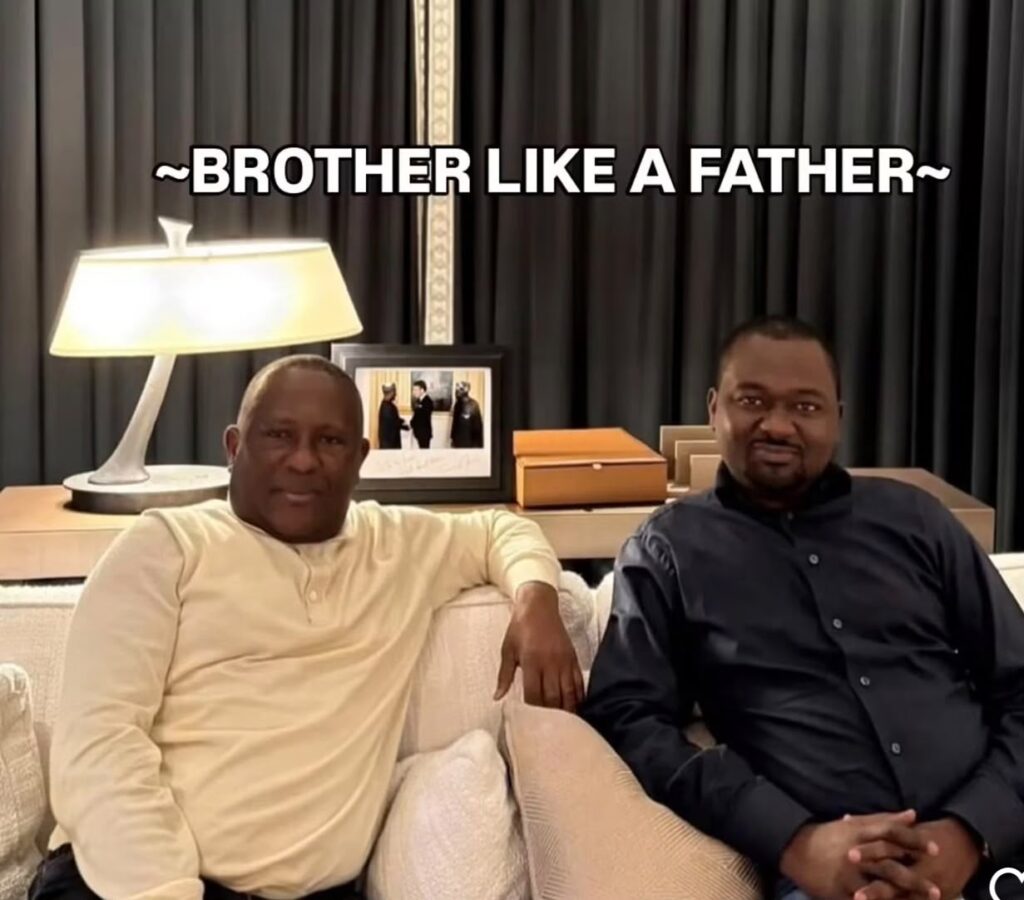
Perhaps that is the more revealing education his father is giving him. Abdul Samad appears less interested in merely showing the young man the assets than in allowing him to understand how those assets breathe.
Factories photograph beautifully, particularly when they rise from acres of land in steel and concrete, but the real life of an industrial empire occurs away from the cameras, in the anxious arithmetic of raw-material costs, shipping schedules, exchange rates, energy, regulation, financing and distribution. The young man who may someday occupy a larger place within such a system must learn that wealth is not sustained by the serenity of the chairman’s office but by countless decisions made under pressure, many of them invisible to the public until one of them goes wrong.
Khalifa’s academic preparation seems almost tailored to the wider world awaiting him. He studied International Relations at Regent’s University London and later earned a Master’s in Management from Georgetown University’s McDonough School of Business, combining an education in states, diplomacy and institutions with the language of management and enterprise.
That marriage of disciplines becomes particularly interesting when considered against the circles into which he has been born and the ones into which he is now increasingly being introduced.
There is, of course, another dimension to his story. Khalifa is one of the children from Abdul Samad Rabiu’s former marriage to Hannatu Musawa, the lawyer, writer and public official who currently serves in President Tinubu’s cabinet as Minister of Art, Culture, Tourism and the Creative Economy. Musawa has herself spoken publicly about her former marriage to Rabiu and the enduring ties between their families.
There is nothing publicly established to suggest that he is preparing to contest an election or embark on a conventional political career. What he possesses instead is exposure: a father situated at the commanding heights of Nigerian private enterprise and a mother operating within the upper reaches of government, two worlds that remain distinct but inevitably encounter each other wherever industry, regulation, investment and public policy meet.
That is why Friday’s visit to President Tinubu is noteworthy without needing to be exaggerated. Its importance lies less in whatever may have been discussed behind closed doors than in the simple fact that Khalifa was there, standing beside his father and becoming familiar with another environment in which his surname, responsibilities and future may eventually carry their own weight.
Such encounters form a peculiar education unavailable in lecture halls. Universities can teach capital allocation and international relations, but they cannot completely teach the temperament of power: how an industrialist speaks to a president without becoming obsequious, how one carries disagreement without converting it into hostility, how old relationships are tended, how new ones are cultivated, or how to distinguish those who are merely attracted to wealth from those whose trust survives difficult seasons.
Those lessons are absorbed by watching.
They reside in airport lounges and factory inspections, private dinners and waiting rooms, board meetings and courtesy visits, in introductions that appear inconsequential until, perhaps ten years later, a name remembered from a handshake becomes the person sitting across a negotiating table.
This is how relationships are inherited, if relationships can ever truly be inherited at all. A father may leave his son factories, shares, houses and an enviable portfolio of assets, but he cannot simply insert forty years of trust into an estate document. The son must accumulate his own credit among bankers, investors, regulators, political leaders, employees and business partners, even when the father’s name opens the first door.
Abdul Samad should understand the intricacies of that inheritance better than most. He was himself born into the formidable commercial tradition of the late Khalifah Isyaku Rabiu, the Kano merchant, scholar and industrialist whose name carried considerable weight long before BUA became the corporate colossus it is today. Abdul Samad inherited a tradition of enterprise but did not merely preserve it; he recast it for another age, moving far beyond the familiar pathways of trading into manufacturing on a scale that turned cement, sugar, flour and other essential commodities into the pillars of a modern industrial fortune.
Now the wheel appears to be turning again.
There is an almost poetic symmetry in the fact that another Khalifa is moving towards the centre of the Rabiu story, although it would be simplistic to describe what is happening as a transfer of the crown. BUA is today too sprawling and professionally structured to be reduced to a princely succession tale, and Kabiru Rabiu remains an important figure in its leadership. The more compelling point is that Khalifa has moved beyond merely being part of the family photograph; he now occupies a position where he can be tested by responsibility, measured by results and introduced gradually to the ecosystem surrounding the family enterprise.
That is how serious succession often begins, not with coronation but with apprenticeship. A young man is first handed work that can expose his weaknesses, then brought into relationships that can test his temperament, before the people who have dealt with his father for decades begin, cautiously, to deal with him in his own right. The family name may secure the introduction, but eventually the young man must demonstrate whether there is substance behind it.
For Abdul Samad, therefore, legacy will one day amount to considerably more than deciding how factories, shares and investments are distributed among heirs. The harder inheritance will be culture, discipline, judgement and the instinct for survival that allowed a family trading heritage to become an industrial institution. Kabiru represents an important part of the generation that travelled that journey alongside him; Khalifa increasingly represents the question of what follows after it.
Seen from that perspective, the young man’s growing presence around his father acquires a meaning beyond privilege. He is watching a man who has spent decades learning the peculiar choreography of Nigerian capitalism, where enterprise lives constantly in conversation with government, regulation, foreign capital, infrastructure and politics without necessarily becoming politics itself. He is being allowed to observe not simply how a fortune is enjoyed but how influence is managed, relationships are preserved and institutions are kept alive through changing governments and economic seasons.
That may ultimately be the most valuable thing Abdul Samad can give him.
Factories can be inherited. Shares can change names on a register. Houses and aircraft can pass from father to son with the neat efficiency of lawyers and trustees. What cannot be transferred so easily is the confidence of people who matter, the discipline to remain composed when markets rebel, the instinct to recognise danger before it announces itself and the ability to enter a room full of powerful men without being diminished by them or intoxicated by their attention. Those things take time.
And perhaps that is the deeper meaning of Khalifa walking beside his father into President Tinubu’s Lagos residence on Friday: the young man is no longer being shown only the empire.
He is being introduced, carefully and gradually, to the world around it.

The Nigerian National Petroleum Company Limited (NNPC Limited) on Tuesday reported a profit after tax of N7.2 trillion for the 2025 financial year, representing a 33 percent increase from the N5.4 trillion recorded in 2024.
The company’s revenue, however, declined by 23.4 percent from N45.075 trillion in 2024 to N34.516 trillion in 2025.
NNPC Limited also reported earnings per share of N35.9, while its taxes, royalties and other remittances to the Federal Government increased by 39 percent to N22.3 trillion.
The company attributed the increase in profit despite lower revenue to improved operational efficiency and cost discipline. Speaking on the results, NNPC Limited Group Chief Executive Officer (GCEO), Engr. Bayo Ojulari, said the decline in revenue was largely due to lower crude oil prices and reduced white-product volumes following market deregulation.
He said the company nonetheless achieved improved operational performance, with crude oil and condensate production reaching a five-year high of 1.77 million barrels per day at its peak in 2025.
Natural gas supply also rose to a three-year high of 7.2 billion standard cubic feet per day, he said.
According to the company, crude oil production for the year stood at 565.8 million barrels, with 278.2 million barrels supplied to domestic refineries.
Gas supply to power plants and commercial customers stood at 473.3 billion standard cubic feet during the year.

JUST IN: Makinde Appoints New Chief of Staff After Ogunwuyi’s Resignation

Federal Government Approved Feeding Allowance For Corps Members

BREAKING: 8 State Governors Out as INEC Releases Final List for 2027 Election

FULL LIST: Top 10 “Tokunbo” Cars You Can Get For ₦3m–₦5m

Former Super Eagles Star Loses Life Savings, Duped By A Pastor of ₦1.2 Billion

