Business
THE BAD LOANS THAT HAUNT ABIODUN ODUBOLA Ex-Chief Risk Officer and FirstBank’s Bad-Loan Scandal

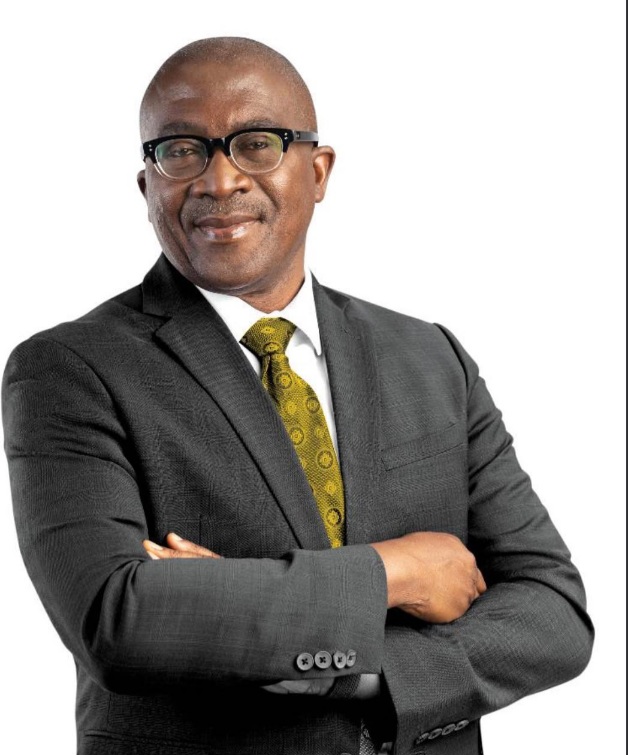
There is something profoundly ironic about a man returning to narrate the history of an institution whose most troubled chapters unfolded while he occupied one of its most consequential offices. History, after all, is not an accommodating mistress. It does not surrender its memory to the convenience of those who wish to revise it, nor does it permit yesterday’s custodians to become today’s critics without occasionally demanding an account of their own stewardship. For Abiodun Odubola, former Executive Director and Chief Risk Officer of First Bank of Nigeria, that uncomfortable reckoning appears particularly relevant as he reportedly prepares to write about the institution he left in 2016.
The irony is difficult to overlook. For while Odubola may have much to say about FirstBank, the bank’s own financial records have an extraordinary story to tell about the years during which he presided over its risk-management machinery. It is a story written not in the comforting language of corporate reminiscence but in the unforgiving arithmetic of impaired loans, deteriorating credit quality, extraordinary provisions and a financial institution struggling to contain the consequences of exposures that had become deeply problematic.
At the centre of that story stands a former Chief Risk Officer whose professional responsibilities were as enormous as the institution he served.
Odubola was appointed FirstBank’s Chief Risk Officer in 2013 and elevated to its board as Executive Director in January 2014. By then, he was no stranger to the intricacies of credit administration, having previously headed the bank’s Credit Analysis and Processing Department. He understood the workings of its lending machinery, the architecture of credit approvals and the delicate intersection between commercial ambition and prudent risk management. Indeed, his own professional résumé, subsequently published on the website of Letshego Holdings, provides a striking account of the authority he wielded.
According to that document, Odubola exercised overall responsibility for FirstBank’s Risk Management Directorate and a credit portfolio exceeding ₦2 trillion. He possessed an individual credit approval limit of ₦2.5 billion and served on management and board credit committees whose approval limits extended to ₦15 billion and ₦59 billion respectively. These were not the privileges of a ceremonial executive. They placed him within the institutional framework through which substantial lending risks were evaluated, monitored and approved, even if final responsibility for particular facilities was shared among different officers and committees.
It is against this background that the deterioration of FirstBank’s loan portfolio assumes an especially troubling significance.
In April 2015, Odubola participated in an investor conference call during which analysts raised concerns about the bank’s exposure to vulnerable sectors of the economy, particularly oil and gas. Questioned about the possibility of rising non-performing loans, he expressed confidence that the institution’s credit quality would remain broadly manageable, projecting a non-performing loan ratio of between three and five per cent for the year.
It was an assurance that would be overtaken by events with devastating speed.
By December 2015, FBN Holdings’ non-performing loan ratio had surged to 18.1 per cent, compared with just 2.9 per cent a year earlier. In monetary terms, non-performing loans climbed from approximately ₦64.8 billion in 2014 to a staggering ₦353.5 billion in 2015. Impairment charges rose from ₦25.9 billion to ₦119.3 billion, while the group’s profit before tax collapsed from ₦94.1 billion to ₦21.5 billion.
The figures were startling, not merely because of their magnitude, but because they revealed just how far the institution’s actual credit experience had departed from the expectations publicly articulated by its chief risk executive.
Certainly, Nigeria’s economic circumstances were becoming increasingly hostile. Declining crude oil prices, the depreciation of the naira and weakening corporate cash flows inflicted considerable damage on borrowers across the banking industry. Yet economic turbulence alone could not explain away every question about FirstBank’s exposure concentration, underwriting discipline and the effectiveness of its internal safeguards.
In June 2016, Standard & Poor’s offered a particularly sobering assessment, identifying weaknesses in the bank’s underwriting standards and lapses in risk management. The international ratings agency disclosed that FirstBank’s 20 largest loans accounted for 43.5 per cent of its total loan portfolio at the end of 2015, while its two largest exposures were already non-performing.
For an institution of FirstBank’s pedigree, such concentration represented an uncomfortable vulnerability. For the executive entrusted with supervising its risk-management structure, it raised questions that cannot reasonably be dismissed as mere historical inconveniences.
And then came the departure.
In 2016, FBN Holdings publicly announced that Odubola would retire as Executive Director and Chief Risk Officer, effective June 30, ostensibly to pursue personal interests. The announcement carried the customary courtesies of corporate separation.
But an account provided to this publication, from someone claiming direct knowledge of the circumstances, disputes the suggestion that his departure was entirely voluntary. According to that account, Odubola was effectively dismissed amid concerns surrounding the bank’s deteriorating credit portfolio. Although this account has not been independently corroborated by dismissal records, and the bank’s official position remains that he retired, the circumstances of the transition warrant closer examination.
Particularly revealing is the language of FirstBank’s own financial disclosures. In its 2015 annual report, FBN Holdings acknowledged serious shortcomings in its risk-management performance and disclosed that a critical review of the culture and practices of the risk-management function had been undertaken. The group also announced structural changes intended to improve underwriting practices and rebuild a more resilient loan portfolio under new leadership.
Those were not casual observations. They were admissions by an institution confronting deep-seated weaknesses in one of the most sensitive areas of its operations.
The task of strengthening that architecture subsequently fell to a new generation of risk-management leadership, including Olusegun Alebiosu, who joined FirstBank as Chief Risk Officer in September 2016. By the end of that year, non-performing loans had risen further, with the ratio reaching 24.4 per cent, underscoring the scale of the legacy challenges confronting the bank.
Years later, FirstBank would publicly acknowledge significant improvements in credit underwriting, loan recoveries and the reduction of non-performing exposures under the restructured risk-management directorate. Such progress did not occur in a vacuum. It reflected the institution’s sustained effort to repair weaknesses exposed during an exceptionally difficult chapter of its corporate history.
All of which makes the prospect of Odubola writing about FirstBank an intriguing development.
There is nothing inherently objectionable about a former executive seeking to document his professional experiences or offering personal reflections on the institution he once served. Indeed, a properly researched account could provide valuable insight into the decisions, personalities and economic circumstances that shaped FirstBank’s fortunes. But the credibility of such an undertaking would depend considerably on its willingness to confront the difficult questions surrounding the author’s own years in office.
For when a bank’s loan portfolio deteriorates so spectacularly, the responsibility for explaining what went wrong cannot be confined to those who inherited the consequences. It must also engage those who helped oversee the machinery through which the risks were assessed and managed.
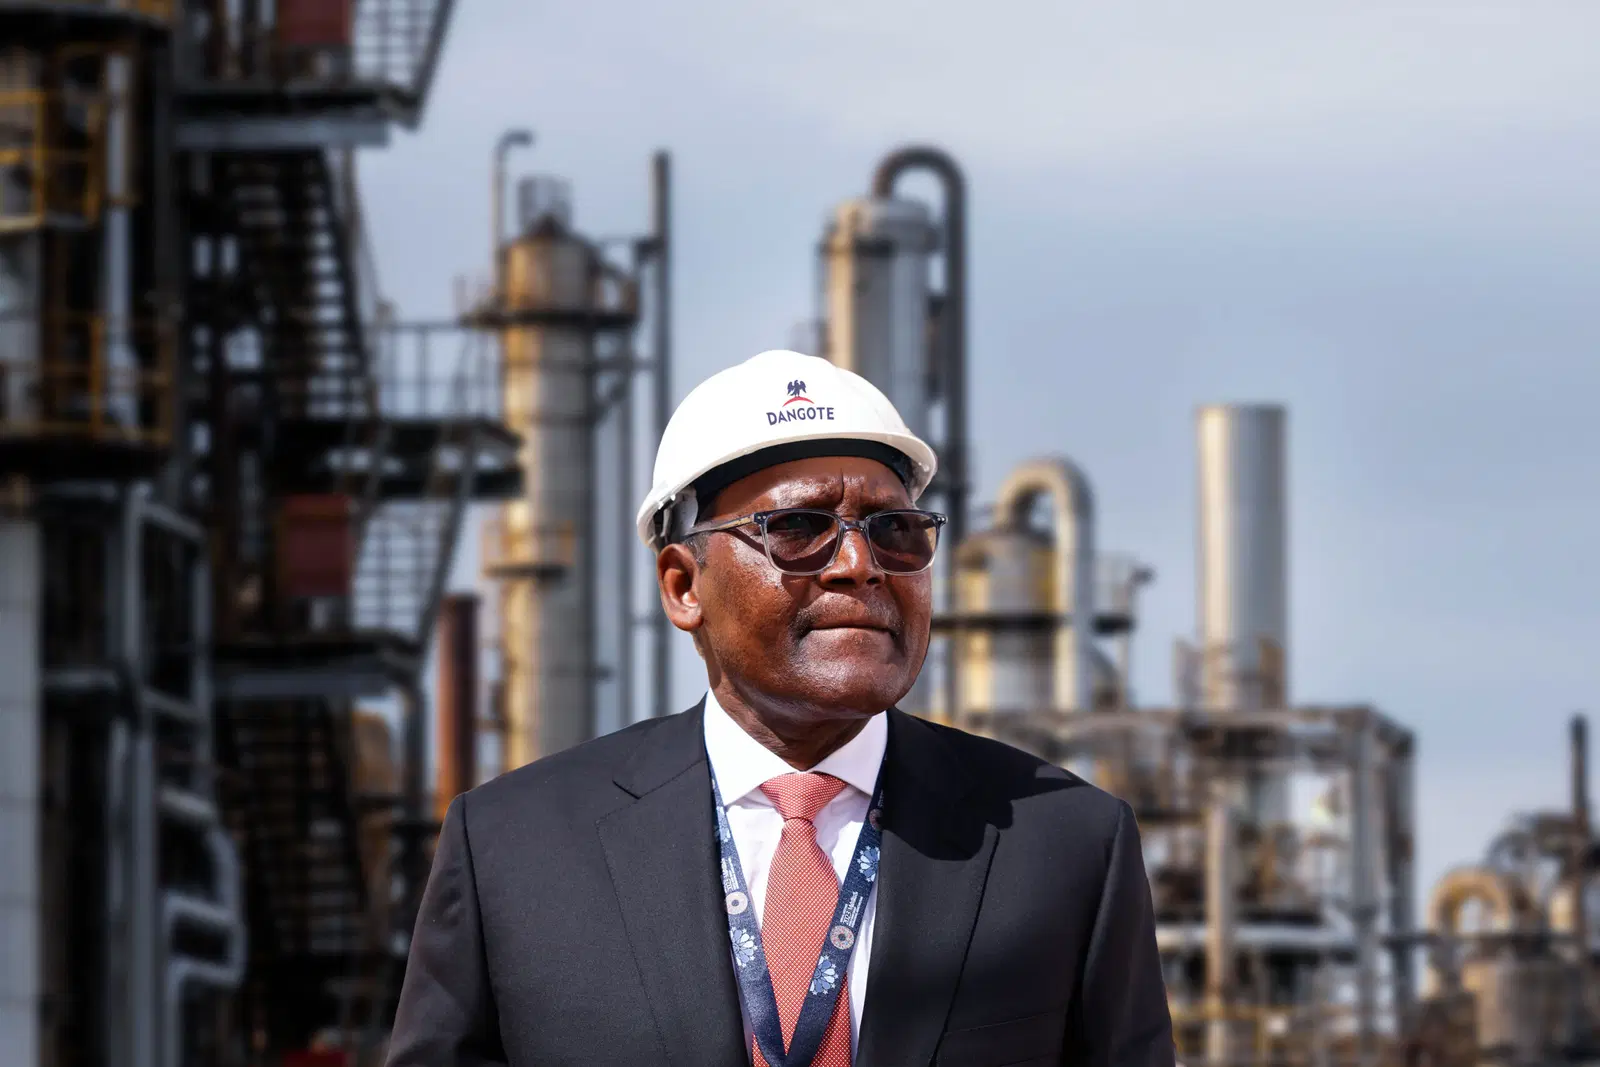
Dangote Group has announced fresh employment opportunities for qualified candidates across several departments at its refinery site.
The vacancies are listed under Dangote-Refinery as the business unit, with the location stated as Dangote Petrochemicals (DPRP) and the department identified as Refinery Site.
The available positions cover procurement, warehouse management, logistics, supply and material planning, compliance, information technology, sustainability and data analytics.
List of Dangote Refinery jobs The 24 positions advertised on the company’s careers platform are:
Industrial Hygienist
Sanitary Inspector
Employee Relations Specialist
Procurement Contract Specialist
Warehouse Team Lead – PPU
Warehouse Manager – PPU
Head, Supply and Material Planning
Head, Logistics & Road Safety Operations
Sales & Operations Planning Manager (S&OP)
Procurement Supplier Specialist
Compliance and Governance Lead
Contract Management Lead
Risk Management Lead (Supply Chain)
Governance and Compliance Specialist
Procurement Supplier Lead
Transport/Dispatch Manager – PPU
Transport/Dispatch Lead – PPU
System Administrative Officer
ESG & Sustainability Manager
ESG / Sustainability Analyst
Lead, System Administration
ISO Management System Coordinator
Data Analytics/System Analyst
Decarbonization Manager
Requirements for Dangote Refinery jobs
The requirements differ depending on the position, and applicants are expected to check the full job description for their preferred vacancy.
Several of the positions require relevant bachelor’s degrees, HNDs or specialised diplomas in fields such as engineering, supply chain management, logistics, business administration, environmental science, public health, information technology and related disciplines.
Some roles also require or favour professional certifications. Depending on the position, these may include certifications in supply chain management, logistics, quality management, information technology and other relevant professional fields.
Work experience is another major requirement, particularly for senior positions.
The experience requested varies from role to role, with some managerial and leadership positions requiring several years of relevant industry experience.
For example, the Warehouse Team Lead – PPU position requires relevant experience in warehouse, logistics or supply chain operations, while the Warehouse Manager – PPU role requires significantly more experience, including managerial exposure.
Applicants for technology-related positions may also need experience with SAP, ERP systems, databases, system administration, Microsoft Excel, Power BI, data analytics and system integration, depending on the vacancy.
For the ISO Management System Coordinator position, candidates are expected to have relevant academic qualifications and experience with international management standards.
The Sanitary Inspector role has more specialised requirements, including qualifications in sanitary inspection, environmental health or public health technology, with related experience preferred.
How to apply for Dangote Refinery jobs Interested candidates should visit the official Dangote careers platform and select the position that matches their qualifications and experience.
Applicants should carefully read the individual job description because the educational qualifications, professional certifications, technical skills and years of experience differ across the 24 positions.
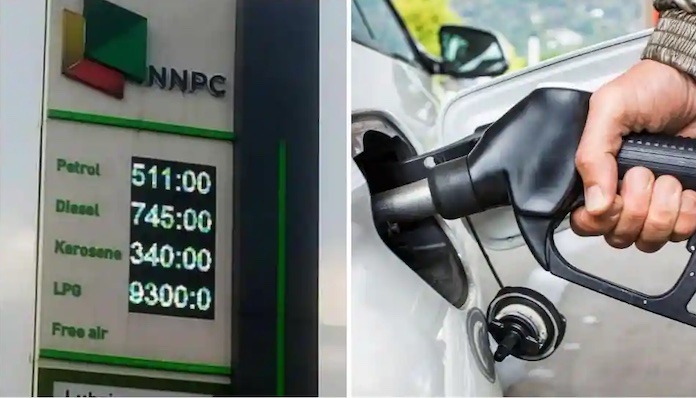
The Nigerian National Petroleum Company Limited (NNPCL) has reduced the pump price of petrol by N5 per litre at its retail outlets in Lagos from N1,360 to N1,355.
Motorists in Lagos and Rivers now pay N1,355 per litre, making them the cheapest locations on NNPC’s updated price list. Abuja buyers are paying N1,370 per litre under the new arrangement.
NNPC petrol prices across Nigeria
Yobe has the highest petrol price at N1,435 per litre, followed by Niger State at N1,433.
Borno, Gombe, Nasarawa and Sokoto are all priced at N1,430 per litre, placing them among the states with the highest fuel prices.
Several south-western states fall within the lower price range. Ogun and Oyo both sit at N1,367, while Osun is priced at N1,358.
Akwa Ibom is at N1,360, just above the Lagos and Rivers rate.
In the south-east, Anambra, Enugu and Imo are each priced at N1,372, with Ebonyi slightly higher at N1,375. Abia is priced at N1,370, the same as Abuja.
Further north, Kaduna is at N1,400, Zamfara at N1,414, while Adamawa, Jigawa, Kebbi, Plateau and Taraba are all priced at N1,420. Bauchi and Kano share a rate of N1,385, while Benue is at N1,410.
In the South-South, Delta is priced at N1,379, Bayelsa and Edo at N1,380, and Cross River at N1,390. Kwara is at N1,375, while Kogi is priced at N1,390. The full breakdown of the new NNPC petrol prices per litre is as follows:
Lagos: N1,355 Rivers: N1,355 Akwa Ibom: N1,360 Osun: N1,358 Ogun: N1,367 Oyo: N1,367 Abia: N1,370 Abuja: N1,370 Anambra: N1,372 Enugu: N1,372 Imo: N1,372 Ebonyi: N1,375 Kwara: N1,375 Ekiti: N1,377 Ondo: N1,377 Delta: N1,379 Bayelsa: N1,380 Edo: N1,380 Bauchi: N1,385 Kano: N1,385 Cross River: N1,390; Kogi: N1,390 Kaduna: N1,400 Benue: N1,410 Zamfara: N1,414 Adamawa: N1,420 Jigawa: N1,420 Kebbi: N1,420 Plateau: N1,420 Taraba: N1,420 Borno: N1,430 Gombe: N1,430 Nasarawa: N1,430 Sokoto: N1,430 Niger: N1,433 Yobe: N1,435
Business
From Kabiru to Khalifa: How Abdul Samad Rabiu is Quietly Positioning his Son in the Corridors of Business and Power
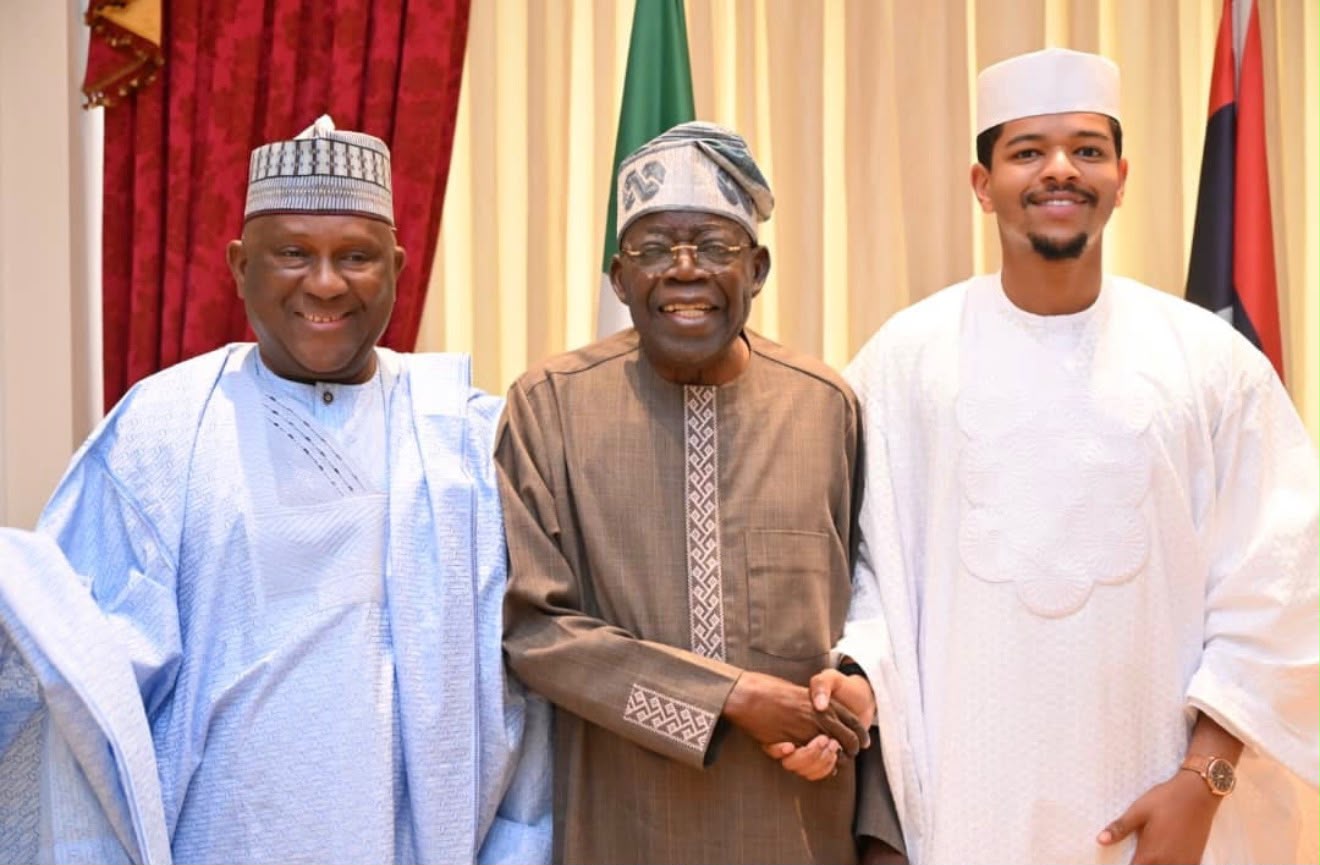
Once, his younger brother Kabiru was one of the familiar family figures around the BUA empire. Now another generation is moving steadily into view as Abdul Samad Rabiu brings his son, Khalifa, closer to the business, relationships and rarefied circles surrounding one of Africa’s largest industrial fortunes.
On Friday, October 2, 2026, when Abdul Samad Rabiu went calling on President Bola Ahmed Tinubu at his Ikoyi residence in Lagos, he did not go alone. Beside the billionaire industrialist was his son, Isyaku Abdulsamad “Khalifa” Rabiu, the young BUA executive whose presence increasingly seems to accompany his father into rooms where business, government and influence converge. Rabiu said the visit afforded an opportunity to reflect on Nigeria’s journey and its future, while other reports confirmed that the BUA chairman was among several prominent business and political figures received by the President that day.
On the surface, there was nothing extraordinary about it. Wealthy fathers travel with their sons, introduce them to friends and take them to important engagements every day. Yet, when the father is Abdul Samad Rabiu, founder of an industrial empire painstakingly assembled over decades, and the son has recently moved into a strategic executive position within that empire, the optics acquire a different texture. A photograph becomes more than a photograph; a handshake begins to look like an introduction, and what appears to be a simple father-and-son outing starts to resemble that ancient ritual through which successful men gradually acquaint the next generation with the world they may one day have to navigate without them.
For those who have watched Abdul Samad through the years, the changing silhouette around him is difficult to miss. There was a time when his younger brother, Kabiru Rabiu, represented one of the most prominent family presences within the BUA establishment, rising through the group’s operations and eventually becoming Group Executive Director, while also serving as a non-executive director of BUA Foods and BUA Cement. He remains firmly embedded in the conglomerate, with more than two decades of experience across edible oils, cement and infrastructure.
Kabiru belongs to Abdul Samad’s generation, however, and that distinction matters because every family empire, no matter how vast or professionally managed, eventually encounters the question that money alone cannot answer: what happens when the generation that built it begins to make room for the generation that must preserve it?
It is within that quiet, complicated passage that Khalifa is increasingly becoming interesting.
His emergence has not arrived with trumpets, ceremonial titles or the public unveiling of a successor. Abdul Samad has not declared him heir to BUA, and nothing in the public record justifies such a conclusion. What has become visible instead is something subtler and perhaps more meaningful: a gradual accumulation of responsibility, exposure and proximity, the three ingredients through which the children of powerful business families are often introduced to the burden behind the privilege.
Khalifa is no longer merely the billionaire’s son appearing occasionally beside his father. On January 29, 2026, BUA Foods appointed him Chief Officer, Global Procurement and Strategic Operations, giving him responsibility for the company’s end-to-end global procurement function and strategic operational initiatives. Before that appointment, he served as Director for Special Operations at BUA Group, where his work included transformation projects, supplier relationships, wheat sourcing, animal-feed production, the commercial reintroduction of BUA rice and other operational initiatives.
There is something instructive about where he has been placed. For the son of one of Africa’s wealthiest industrialists, a grand office and ornamental designation would have been easy enough to manufacture, the sort of corporate embroidery with which family businesses sometimes decorate heirs who have yet to acquire the scars of enterprise. Khalifa, however, has been taken closer to procurement, supply chains and operations, into the less glamorous entrails of an industrial organisation where fortunes are not discussed in abstract terms but depend on the relentless movement of wheat, sugar, machinery, ships, suppliers, currencies, warehouses and markets.
Perhaps that is the more revealing education his father is giving him. Abdul Samad appears less interested in merely showing the young man the assets than in allowing him to understand how those assets breathe.
Factories photograph beautifully, particularly when they rise from acres of land in steel and concrete, but the real life of an industrial empire occurs away from the cameras, in the anxious arithmetic of raw-material costs, shipping schedules, exchange rates, energy, regulation, financing and distribution. The young man who may someday occupy a larger place within such a system must learn that wealth is not sustained by the serenity of the chairman’s office but by countless decisions made under pressure, many of them invisible to the public until one of them goes wrong.
Khalifa’s academic preparation seems almost tailored to the wider world awaiting him. He studied International Relations at Regent’s University London and later earned a Master’s in Management from Georgetown University’s McDonough School of Business, combining an education in states, diplomacy and institutions with the language of management and enterprise.
That marriage of disciplines becomes particularly interesting when considered against the circles into which he has been born and the ones into which he is now increasingly being introduced.
There is, of course, another dimension to his story. Khalifa is one of the children from Abdul Samad Rabiu’s former marriage to Hannatu Musawa, the lawyer, writer and public official who currently serves in President Tinubu’s cabinet as Minister of Art, Culture, Tourism and the Creative Economy. Musawa has herself spoken publicly about her former marriage to Rabiu and the enduring ties between their families.
There is nothing publicly established to suggest that he is preparing to contest an election or embark on a conventional political career. What he possesses instead is exposure: a father situated at the commanding heights of Nigerian private enterprise and a mother operating within the upper reaches of government, two worlds that remain distinct but inevitably encounter each other wherever industry, regulation, investment and public policy meet.
That is why Friday’s visit to President Tinubu is noteworthy without needing to be exaggerated. Its importance lies less in whatever may have been discussed behind closed doors than in the simple fact that Khalifa was there, standing beside his father and becoming familiar with another environment in which his surname, responsibilities and future may eventually carry their own weight.
Such encounters form a peculiar education unavailable in lecture halls. Universities can teach capital allocation and international relations, but they cannot completely teach the temperament of power: how an industrialist speaks to a president without becoming obsequious, how one carries disagreement without converting it into hostility, how old relationships are tended, how new ones are cultivated, or how to distinguish those who are merely attracted to wealth from those whose trust survives difficult seasons.
Those lessons are absorbed by watching.
They reside in airport lounges and factory inspections, private dinners and waiting rooms, board meetings and courtesy visits, in introductions that appear inconsequential until, perhaps ten years later, a name remembered from a handshake becomes the person sitting across a negotiating table.
This is how relationships are inherited, if relationships can ever truly be inherited at all. A father may leave his son factories, shares, houses and an enviable portfolio of assets, but he cannot simply insert forty years of trust into an estate document. The son must accumulate his own credit among bankers, investors, regulators, political leaders, employees and business partners, even when the father’s name opens the first door.
Abdul Samad should understand the intricacies of that inheritance better than most. He was himself born into the formidable commercial tradition of the late Khalifah Isyaku Rabiu, the Kano merchant, scholar and industrialist whose name carried considerable weight long before BUA became the corporate colossus it is today. Abdul Samad inherited a tradition of enterprise but did not merely preserve it; he recast it for another age, moving far beyond the familiar pathways of trading into manufacturing on a scale that turned cement, sugar, flour and other essential commodities into the pillars of a modern industrial fortune.
Now the wheel appears to be turning again.
There is an almost poetic symmetry in the fact that another Khalifa is moving towards the centre of the Rabiu story, although it would be simplistic to describe what is happening as a transfer of the crown. BUA is today too sprawling and professionally structured to be reduced to a princely succession tale, and Kabiru Rabiu remains an important figure in its leadership. The more compelling point is that Khalifa has moved beyond merely being part of the family photograph; he now occupies a position where he can be tested by responsibility, measured by results and introduced gradually to the ecosystem surrounding the family enterprise.
That is how serious succession often begins, not with coronation but with apprenticeship. A young man is first handed work that can expose his weaknesses, then brought into relationships that can test his temperament, before the people who have dealt with his father for decades begin, cautiously, to deal with him in his own right. The family name may secure the introduction, but eventually the young man must demonstrate whether there is substance behind it.
For Abdul Samad, therefore, legacy will one day amount to considerably more than deciding how factories, shares and investments are distributed among heirs. The harder inheritance will be culture, discipline, judgement and the instinct for survival that allowed a family trading heritage to become an industrial institution. Kabiru represents an important part of the generation that travelled that journey alongside him; Khalifa increasingly represents the question of what follows after it.
Seen from that perspective, the young man’s growing presence around his father acquires a meaning beyond privilege. He is watching a man who has spent decades learning the peculiar choreography of Nigerian capitalism, where enterprise lives constantly in conversation with government, regulation, foreign capital, infrastructure and politics without necessarily becoming politics itself. He is being allowed to observe not simply how a fortune is enjoyed but how influence is managed, relationships are preserved and institutions are kept alive through changing governments and economic seasons.
That may ultimately be the most valuable thing Abdul Samad can give him.
Factories can be inherited. Shares can change names on a register. Houses and aircraft can pass from father to son with the neat efficiency of lawyers and trustees. What cannot be transferred so easily is the confidence of people who matter, the discipline to remain composed when markets rebel, the instinct to recognise danger before it announces itself and the ability to enter a room full of powerful men without being diminished by them or intoxicated by their attention. Those things take time.
And perhaps that is the deeper meaning of Khalifa walking beside his father into President Tinubu’s Lagos residence on Friday: the young man is no longer being shown only the empire.
He is being introduced, carefully and gradually, to the world around it.

A Legacy Written in Miles, Sweat and Splendour

THE BAD LOANS THAT HAUNT ABIODUN ODUBOLA Ex-Chief Risk Officer and FirstBank’s Bad-Loan Scandal


