Business
FG Releases List of Approved Centres For Nigerians To Register to Get N30k Monthly [Full List]

The Federal Government has made available an official online register of approved training centres for Nigerians interested in its Technical and Vocational Education and Training (TVET) programme.
The initiative offers eligible participants free vocational training and a monthly stipend of N30,000, providing an opportunity to acquire practical skills while receiving financial support.
The approved centres can be checked through the National Board for Technical Education (NBTE) register and the Federal Ministry of Education’s TVET portal.
The programme is designed to equip Nigerians with employable skills, encourage entrepreneurship and improve access to vocational education amid rising unemployment and economic pressures.
The NBTE maintains an online register covering vocational institutions, Skills Training Centres (STCs), Vocational Enterprise Institutions (VEIs) and other recognised training providers. Master Craft Persons (MCPs) are also involved in delivering practical, industry-based training under the TVET initiative.
The register allows prospective trainees to identify recognised institutions rather than relying on unverified lists circulating on social media.
Training providers are spread across different states, giving applicants opportunities to explore centres offering their preferred vocational skills.
However, applicants should understand that an institution’s appearance on a register does not automatically guarantee admission or stipend payments.
Applicants seeking recognised training centres can follow these steps:
Visit the official NBTE register.
Open the Federal Ministry of Education TVET portal to review programme information.
Search available institutions using the location, ownership or programme filters provided. Check whether the preferred centre offers the desired vocational course.
Follow the official application and placement instructions before reporting to any training centre.
Applicants should regularly monitor their registration dashboard and contact details for official updates concerning admission, training schedules and centre assignments.
The programme covers practical trades intended to prepare participants for employment, self-employment and small business opportunities.
Available training areas may include fashion design, tailoring, electrical installation, plumbing, welding, solar installation, automobile repairs and information technology.
The specific courses offered depend on the training provider and approved programme arrangements.
Participants are expected to receive hands-on instruction that can help them develop technical competence and improve their prospects in the labour market.
Under the TVET programme, eligible trainees are expected to receive a monthly upkeep allowance of N30,000 during the applicable training period.
However, registration alone does not guarantee payment.
Applicants must satisfy the programme’s eligibility, selection and participation requirements.
The stipend is intended to support trainees while they acquire practical skills, rather than serve as an unconditional cash grant. Prospective applicants should also avoid individuals demanding payment to secure admission, confirm centre placement or release allowances.
Official programme information should be obtained directly from the Federal Ministry of Education and NBTE platforms.
The NBTE register currently displays 3,471 institutions across its various categories, including 2,362 Skills Training Centres and 322 Master Craft Persons.
These figures cover the wider NBTE register and should not be interpreted as the number of available TVET programme placements.
The per litre price of Premium Motor Spirit (PMS), popularly known as fuel or petrol, has witnessed a fresh reduction across Nigeria.Nigeria Travel Guides
The price cuts followed a decline in global crude oil prices, as well as reductions in the gantry price of petrol from the Dangote Refinery and the landing cost of imported fuel, Naija News understands.
According to Daily Post, a check by journalists showed that depot owners are currently selling petrol between ₦1,175 and ₦1,215 per litre.
In Abuja, the pump price ranges between ₦1,325 and ₦1,420 per litre.
The Nigerian National Petroleum Company Limited (NNPCL), MRS and other filling stations have also reduced their pump prices by between ₦9 and ₦80 per litre in less than two weeks, Naija News reports.Naija News subscription
The decline in local petrol prices comes amid a drop in the cost of crude oil in the international market.
As of the time of filing this report, Brent crude was selling at about $95 per barrel, while West Texas Intermediate (WTI) stood at $88 per barrel.
Global oil prices have eased in recent days despite continued tensions in the Middle East.
The fall in crude oil prices has also affected the cost of supplying petrol to Nigeria, leading to lower prices at the local market.Nigeria Travel Guides
Dangote Refinery’s petrol gantry price, which stood at about ₦1,350 per litre in mid-September, dropped to approximately ₦1,159 per litre in early November 2026.
Similarly, the landing cost of imported petrol fell to ₦1,063 per litre on November 13, 2026, from ₦1,384.82 per litre around September 25.
The reductions in the prices of locally refined and imported petrol have since reflected in depot prices and the amounts charged by filling stations.
The latest development offers some relief to motorists and other petrol users who have had to contend with high fuel prices.
The National Pension Commission (PenCom) says the Federal Government has settled outstanding retirement benefits under the Contributory Pension Scheme, although its director-general has promised to investigate complaints from pensioners who say they have not received payments.
Omolola Oloworaran defended the commission’s payment record during an Arise News interview, in which she also explained the funding behind the new ₦52,500 minimum monthly pension and the limits of the PenCare healthcare programme.
Interviewers challenged her assurances with complaints attributed to a former director of news at Voice of Nigeria and some pensioners of the defunct Nigeria Airways. Oloworaran requested details of the individual cases and undertook to establish what remained unresolved.
“I disagree with the characterisation that the majority of retirees have not received their pension,” she said.
She attributed the settlement of federal CPS liabilities to a ₦758 billion government intervention bond, maintaining that the outstanding benefits covered by that intervention had been paid.
The interview also addressed how PenCom intends to improve retirement income for pensioners whose existing monthly payments fall below the newly approved minimum.
Under the Minimum Pension Guarantee, eligible CPS retirees receiving less than ₦52,500 monthly will receive a supplement that brings their pension to that amount. The arrangement targets pensioners with insufficient retirement savings to support payments at the approved level.
At the programme’s launch in Abuja, PenCom identified 173,209 eligible beneficiaries. Private-sector retirees accounted for 54 per cent of that number, federal retirees 34 per cent and state retirees 12 per cent, according to Voice of Nigeria’s report of the ceremony.
Oloworaran said an actuary assessed the programme’s projected obligations before the commission settled on ₦52,500, equivalent to 75 per cent of the current national minimum wage.
She acknowledged concerns that inflation could reduce the purchasing power of the payment. PenCom would review the amount, she said, while considering both changes in living costs and the resources available to sustain the guarantee.
Her priority, she explained, was to avoid introducing a payment that the pension system would subsequently struggle to maintain.
The Pension Protection Fund will finance the supplements. Oloworaran put the pension industry’s contribution at ₦50 billion and the Federal Government’s contribution at ₦350 billion.
She said the government’s payment included accumulated contributions that previous administrations had not provided. Before the current administration, she added, the fund held approximately ₦38 billion, contributed by pension industry operators.
Those operators include pension fund administrators, closed pension fund administrators and pension fund custodians. PenCom now wants wider participation from private-sector employers to support the guarantee over the longer term.
“The aim is to broaden this out to bring private sector into the scheme as well,” she said.
Oloworaran estimated that the resources currently available could sustain the programme for at least 10 years on conservative assumptions. She nevertheless said the commission needed to plan across the longer period during which beneficiaries would require support.
State governments must also contribute to the Pension Protection Fund before their retirees can access the minimum pension arrangement, she explained in separate remarks reported by BusinessDay. PenCom is developing the participation arrangements for states.
Alongside the income supplement, Oloworaran outlined how eligible low-income retirees can obtain healthcare through PenCare.
She directed prospective beneficiaries to their pension fund administrators for enrolment assistance and collection of physical healthcare cards. Participating health maintenance organisations will identify the hospitals available to them and explain the services included in their cover.
The programme provides access to a defined package of care, including one general health check each year. Oloworaran cautioned that the existing package does not yet cover severe illnesses or more extensive treatment.
PenCom is working on a separate critical illness fund, she said. That proposed arrangement would have spending limits tied to the money available.
Returning to complaints about unpaid benefits, Oloworaran distinguished the CPS from the older defined-benefit arrangements administered by the Pension Transitional Arrangement Directorate (PTAD).
She said the Federal Government funds the legacy arrangement monthly and that payment delays, when they occur, are addressed.
“As of today, I am not aware of any pending payments with PTAD,” she said.
Business
THE BAD LOANS THAT HAUNT ABIODUN ODUBOLA Ex-Chief Risk Officer and FirstBank’s Bad-Loan Scandal
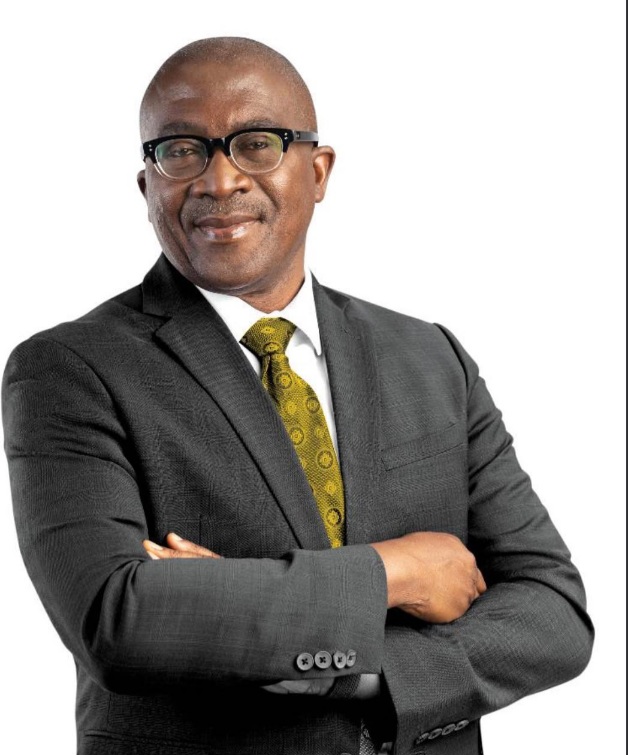
There is something profoundly ironic about a man returning to narrate the history of an institution whose most troubled chapters unfolded while he occupied one of its most consequential offices. History, after all, is not an accommodating mistress. It does not surrender its memory to the convenience of those who wish to revise it, nor does it permit yesterday’s custodians to become today’s critics without occasionally demanding an account of their own stewardship. For Abiodun Odubola, former Executive Director and Chief Risk Officer of First Bank of Nigeria, that uncomfortable reckoning appears particularly relevant as he reportedly prepares to write about the institution he left in 2016.
The irony is difficult to overlook. For while Odubola may have much to say about FirstBank, the bank’s own financial records have an extraordinary story to tell about the years during which he presided over its risk-management machinery. It is a story written not in the comforting language of corporate reminiscence but in the unforgiving arithmetic of impaired loans, deteriorating credit quality, extraordinary provisions and a financial institution struggling to contain the consequences of exposures that had become deeply problematic.
At the centre of that story stands a former Chief Risk Officer whose professional responsibilities were as enormous as the institution he served.
Odubola was appointed FirstBank’s Chief Risk Officer in 2013 and elevated to its board as Executive Director in January 2014. By then, he was no stranger to the intricacies of credit administration, having previously headed the bank’s Credit Analysis and Processing Department. He understood the workings of its lending machinery, the architecture of credit approvals and the delicate intersection between commercial ambition and prudent risk management. Indeed, his own professional résumé, subsequently published on the website of Letshego Holdings, provides a striking account of the authority he wielded.
According to that document, Odubola exercised overall responsibility for FirstBank’s Risk Management Directorate and a credit portfolio exceeding ₦2 trillion. He possessed an individual credit approval limit of ₦2.5 billion and served on management and board credit committees whose approval limits extended to ₦15 billion and ₦59 billion respectively. These were not the privileges of a ceremonial executive. They placed him within the institutional framework through which substantial lending risks were evaluated, monitored and approved, even if final responsibility for particular facilities was shared among different officers and committees.
It is against this background that the deterioration of FirstBank’s loan portfolio assumes an especially troubling significance.
In April 2015, Odubola participated in an investor conference call during which analysts raised concerns about the bank’s exposure to vulnerable sectors of the economy, particularly oil and gas. Questioned about the possibility of rising non-performing loans, he expressed confidence that the institution’s credit quality would remain broadly manageable, projecting a non-performing loan ratio of between three and five per cent for the year.
It was an assurance that would be overtaken by events with devastating speed.
By December 2015, FBN Holdings’ non-performing loan ratio had surged to 18.1 per cent, compared with just 2.9 per cent a year earlier. In monetary terms, non-performing loans climbed from approximately ₦64.8 billion in 2014 to a staggering ₦353.5 billion in 2015. Impairment charges rose from ₦25.9 billion to ₦119.3 billion, while the group’s profit before tax collapsed from ₦94.1 billion to ₦21.5 billion.
The figures were startling, not merely because of their magnitude, but because they revealed just how far the institution’s actual credit experience had departed from the expectations publicly articulated by its chief risk executive.
Certainly, Nigeria’s economic circumstances were becoming increasingly hostile. Declining crude oil prices, the depreciation of the naira and weakening corporate cash flows inflicted considerable damage on borrowers across the banking industry. Yet economic turbulence alone could not explain away every question about FirstBank’s exposure concentration, underwriting discipline and the effectiveness of its internal safeguards.
In June 2016, Standard & Poor’s offered a particularly sobering assessment, identifying weaknesses in the bank’s underwriting standards and lapses in risk management. The international ratings agency disclosed that FirstBank’s 20 largest loans accounted for 43.5 per cent of its total loan portfolio at the end of 2015, while its two largest exposures were already non-performing.
For an institution of FirstBank’s pedigree, such concentration represented an uncomfortable vulnerability. For the executive entrusted with supervising its risk-management structure, it raised questions that cannot reasonably be dismissed as mere historical inconveniences.
And then came the departure.
In 2016, FBN Holdings publicly announced that Odubola would retire as Executive Director and Chief Risk Officer, effective June 30, ostensibly to pursue personal interests. The announcement carried the customary courtesies of corporate separation.
But an account provided to this publication, from someone claiming direct knowledge of the circumstances, disputes the suggestion that his departure was entirely voluntary. According to that account, Odubola was effectively dismissed amid concerns surrounding the bank’s deteriorating credit portfolio. Although this account has not been independently corroborated by dismissal records, and the bank’s official position remains that he retired, the circumstances of the transition warrant closer examination.
Particularly revealing is the language of FirstBank’s own financial disclosures. In its 2015 annual report, FBN Holdings acknowledged serious shortcomings in its risk-management performance and disclosed that a critical review of the culture and practices of the risk-management function had been undertaken. The group also announced structural changes intended to improve underwriting practices and rebuild a more resilient loan portfolio under new leadership.
Those were not casual observations. They were admissions by an institution confronting deep-seated weaknesses in one of the most sensitive areas of its operations.
The task of strengthening that architecture subsequently fell to a new generation of risk-management leadership, including Olusegun Alebiosu, who joined FirstBank as Chief Risk Officer in September 2016. By the end of that year, non-performing loans had risen further, with the ratio reaching 24.4 per cent, underscoring the scale of the legacy challenges confronting the bank.
Years later, FirstBank would publicly acknowledge significant improvements in credit underwriting, loan recoveries and the reduction of non-performing exposures under the restructured risk-management directorate. Such progress did not occur in a vacuum. It reflected the institution’s sustained effort to repair weaknesses exposed during an exceptionally difficult chapter of its corporate history.
All of which makes the prospect of Odubola writing about FirstBank an intriguing development.
There is nothing inherently objectionable about a former executive seeking to document his professional experiences or offering personal reflections on the institution he once served. Indeed, a properly researched account could provide valuable insight into the decisions, personalities and economic circumstances that shaped FirstBank’s fortunes. But the credibility of such an undertaking would depend considerably on its willingness to confront the difficult questions surrounding the author’s own years in office.
For when a bank’s loan portfolio deteriorates so spectacularly, the responsibility for explaining what went wrong cannot be confined to those who inherited the consequences. It must also engage those who helped oversee the machinery through which the risks were assessed and managed.

FG Releases List of Approved Centres For Nigerians To Register to Get N30k Monthly [Full List]

Jonathan’s Second Wife Reveals What Many Don’t Know About Her Marriage to Ex-President

₦70,000 Allowance: 4 Things Workers Must Know Before Payment Commences


-
 News1 day ago
₦70,000 Allowance: 4 Things Workers Must Know Before Payment Commences
-
News2 days ago
FG Announces Payment Date for Newly Approved Workers’ Allowance
-
 Business2 days ago
Tinubu’s Government Pays All Contributory Pension Scheme Retirees
-
 Politics2 days ago
BREAKING: Popular Governorship Candidate Dumps Party Ahead 2027 Election
-
 Business2 days ago
BREAKING: Petrol Price Drops Across Nigeria
-
 Entertainment1 day ago
JUST IN: Tragedy Hits Nollywood Again As Another Actress Dies [PHOTO]
-
 Lifestyle5 hours ago
Jonathan’s Second Wife Reveals What Many Don’t Know About Her Marriage to Ex-President