Business
CBN Lauds Nigeria’s Instant Payment System

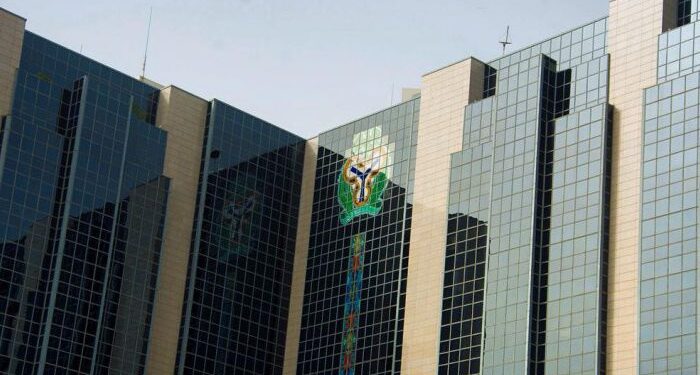
The Central Bank of Nigeria has declared the country’s instant payment system as one of the most advanced globally, citing years of reforms and innovation that have reshaped the nation’s financial landscape.
Director of Payments System Policy at the CBN, Mr Musa Jimoh, made this known on Thursday during the FintechNGR Quarter Two Regulators’ Forum Webinar, themed “Beyond Compliance: Unlocking Innovation with Nigeria’s Open Banking Framework.”
According to Jimoh, Nigeria’s payment ecosystem has evolved significantly, fuelled by a blend of fintech innovation, progressive regulation, and shifting consumer behaviour.
“Our payments happen within seconds, and that’s a very big one for Nigeria as a country,” he said, describing the instant payment system as a reflection of the country’s drive for innovation and financial inclusion.
The forum, which brought together key players in the financial technology space, explored the potential of open banking to deepen financial services and promote collaboration among institutions.
Jimoh noted that the CBN had made deliberate efforts over the years to modernise Nigeria’s financial system, starting as far back as 2006 when it first inaugurated a national payment system vision.
“The journey of payment system development in Nigeria has been long. It started about 2006 when the CBN inaugurated its first payment system vision. The objective was to prepare a roadmap for the development of the payment system in Nigeria,” he said.
One of the pivotal moments, he explained, came in 2010 when the apex bank mandated a switch from magnetic stripe cards to chip-and-PIN cards, a move that led to the widespread adoption of more secure EMV payment cards.
“This was a major turning point for Nigeria,” he noted.
Jimoh traced further developments in the ecosystem to regulatory interventions such as Know Your Customer protocols, mobile banking, agent banking, mobile money, and the cashless policy.
“Today, Nigeria has over 160 different licenses granted to institutions for financial and payment services,” he revealed, adding that financial institutions and switching companies had also upgraded their infrastructure to handle increasing transaction volumes.
He also cited the biometric-based Bank Verification Number as a landmark policy that enabled secure customer identity across platforms.
Touching on the relevance of open banking, Jimoh said it had the potential to boost innovation by enabling developers to build new financial products using customer-permissioned data held by banks.
“Banks are holding onto vast amounts of data that could be leveraged to develop innovative financial products and services. The CBN believes that open banking can help address this challenge by allowing developers to access bank data and create innovative financial products and services. The data must be permissioned, and the customer must give consent before it can be used,” he said.
However, he acknowledged that challenges remain in the implementation of open banking, particularly around the standardisation of APIs and cybersecurity.
To address these, Jimoh said the CBN had set up specialised workstreams focused on solving technical and policy issues surrounding open banking.
“The CBN aims to create an environment where openness, inclusiveness, and innovation drive national economic resilience and prosperity. With a robust regulatory framework, standardised API, and collaboration among stakeholders, open banking could transform Nigeria’s financial landscape,” he said.
Jimoh concluded by reiterating the central bank’s commitment to working with the private sector and regulators to advance innovation and deepen access to financial services across Nigeria.
“The CBN has released regulations and guidelines on open banking and established a regulatory sandbox to support innovation,” he added.
Punchng.com



Business
THE BAD LOANS THAT HAUNT ABIODUN ODUBOLA Ex-Chief Risk Officer and FirstBank’s Bad-Loan Scandal
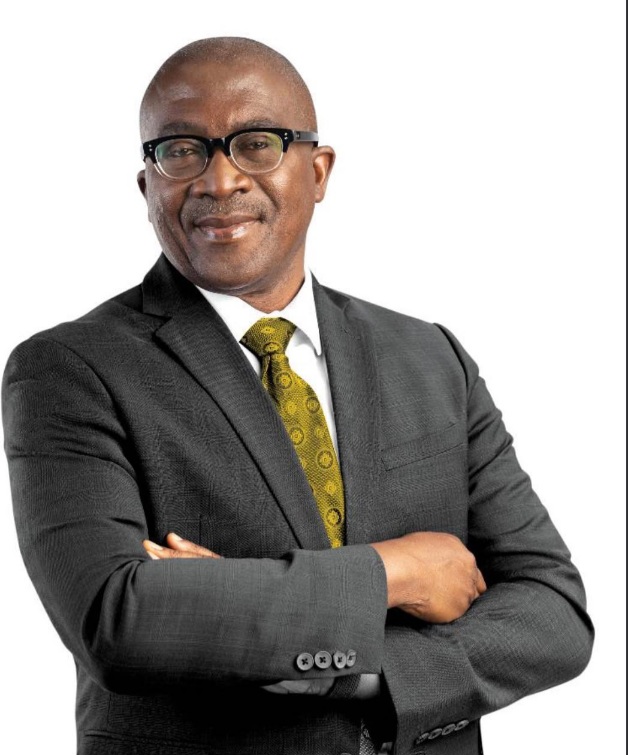
There is something profoundly ironic about a man returning to narrate the history of an institution whose most troubled chapters unfolded while he occupied one of its most consequential offices. History, after all, is not an accommodating mistress. It does not surrender its memory to the convenience of those who wish to revise it, nor does it permit yesterday’s custodians to become today’s critics without occasionally demanding an account of their own stewardship. For Abiodun Odubola, former Executive Director and Chief Risk Officer of First Bank of Nigeria, that uncomfortable reckoning appears particularly relevant as he reportedly prepares to write about the institution he left in 2016.
The irony is difficult to overlook. For while Odubola may have much to say about FirstBank, the bank’s own financial records have an extraordinary story to tell about the years during which he presided over its risk-management machinery. It is a story written not in the comforting language of corporate reminiscence but in the unforgiving arithmetic of impaired loans, deteriorating credit quality, extraordinary provisions and a financial institution struggling to contain the consequences of exposures that had become deeply problematic.
At the centre of that story stands a former Chief Risk Officer whose professional responsibilities were as enormous as the institution he served.
Odubola was appointed FirstBank’s Chief Risk Officer in 2013 and elevated to its board as Executive Director in January 2014. By then, he was no stranger to the intricacies of credit administration, having previously headed the bank’s Credit Analysis and Processing Department. He understood the workings of its lending machinery, the architecture of credit approvals and the delicate intersection between commercial ambition and prudent risk management. Indeed, his own professional résumé, subsequently published on the website of Letshego Holdings, provides a striking account of the authority he wielded.
According to that document, Odubola exercised overall responsibility for FirstBank’s Risk Management Directorate and a credit portfolio exceeding ₦2 trillion. He possessed an individual credit approval limit of ₦2.5 billion and served on management and board credit committees whose approval limits extended to ₦15 billion and ₦59 billion respectively. These were not the privileges of a ceremonial executive. They placed him within the institutional framework through which substantial lending risks were evaluated, monitored and approved, even if final responsibility for particular facilities was shared among different officers and committees.
It is against this background that the deterioration of FirstBank’s loan portfolio assumes an especially troubling significance.
In April 2015, Odubola participated in an investor conference call during which analysts raised concerns about the bank’s exposure to vulnerable sectors of the economy, particularly oil and gas. Questioned about the possibility of rising non-performing loans, he expressed confidence that the institution’s credit quality would remain broadly manageable, projecting a non-performing loan ratio of between three and five per cent for the year.
It was an assurance that would be overtaken by events with devastating speed.
By December 2015, FBN Holdings’ non-performing loan ratio had surged to 18.1 per cent, compared with just 2.9 per cent a year earlier. In monetary terms, non-performing loans climbed from approximately ₦64.8 billion in 2014 to a staggering ₦353.5 billion in 2015. Impairment charges rose from ₦25.9 billion to ₦119.3 billion, while the group’s profit before tax collapsed from ₦94.1 billion to ₦21.5 billion.
The figures were startling, not merely because of their magnitude, but because they revealed just how far the institution’s actual credit experience had departed from the expectations publicly articulated by its chief risk executive.
Certainly, Nigeria’s economic circumstances were becoming increasingly hostile. Declining crude oil prices, the depreciation of the naira and weakening corporate cash flows inflicted considerable damage on borrowers across the banking industry. Yet economic turbulence alone could not explain away every question about FirstBank’s exposure concentration, underwriting discipline and the effectiveness of its internal safeguards.
In June 2016, Standard & Poor’s offered a particularly sobering assessment, identifying weaknesses in the bank’s underwriting standards and lapses in risk management. The international ratings agency disclosed that FirstBank’s 20 largest loans accounted for 43.5 per cent of its total loan portfolio at the end of 2015, while its two largest exposures were already non-performing.
For an institution of FirstBank’s pedigree, such concentration represented an uncomfortable vulnerability. For the executive entrusted with supervising its risk-management structure, it raised questions that cannot reasonably be dismissed as mere historical inconveniences.
And then came the departure.
In 2016, FBN Holdings publicly announced that Odubola would retire as Executive Director and Chief Risk Officer, effective June 30, ostensibly to pursue personal interests. The announcement carried the customary courtesies of corporate separation.
But an account provided to this publication, from someone claiming direct knowledge of the circumstances, disputes the suggestion that his departure was entirely voluntary. According to that account, Odubola was effectively dismissed amid concerns surrounding the bank’s deteriorating credit portfolio. Although this account has not been independently corroborated by dismissal records, and the bank’s official position remains that he retired, the circumstances of the transition warrant closer examination.
Particularly revealing is the language of FirstBank’s own financial disclosures. In its 2015 annual report, FBN Holdings acknowledged serious shortcomings in its risk-management performance and disclosed that a critical review of the culture and practices of the risk-management function had been undertaken. The group also announced structural changes intended to improve underwriting practices and rebuild a more resilient loan portfolio under new leadership.
Those were not casual observations. They were admissions by an institution confronting deep-seated weaknesses in one of the most sensitive areas of its operations.
The task of strengthening that architecture subsequently fell to a new generation of risk-management leadership, including Olusegun Alebiosu, who joined FirstBank as Chief Risk Officer in September 2016. By the end of that year, non-performing loans had risen further, with the ratio reaching 24.4 per cent, underscoring the scale of the legacy challenges confronting the bank.
Years later, FirstBank would publicly acknowledge significant improvements in credit underwriting, loan recoveries and the reduction of non-performing exposures under the restructured risk-management directorate. Such progress did not occur in a vacuum. It reflected the institution’s sustained effort to repair weaknesses exposed during an exceptionally difficult chapter of its corporate history.
All of which makes the prospect of Odubola writing about FirstBank an intriguing development.
There is nothing inherently objectionable about a former executive seeking to document his professional experiences or offering personal reflections on the institution he once served. Indeed, a properly researched account could provide valuable insight into the decisions, personalities and economic circumstances that shaped FirstBank’s fortunes. But the credibility of such an undertaking would depend considerably on its willingness to confront the difficult questions surrounding the author’s own years in office.
For when a bank’s loan portfolio deteriorates so spectacularly, the responsibility for explaining what went wrong cannot be confined to those who inherited the consequences. It must also engage those who helped oversee the machinery through which the risks were assessed and managed.
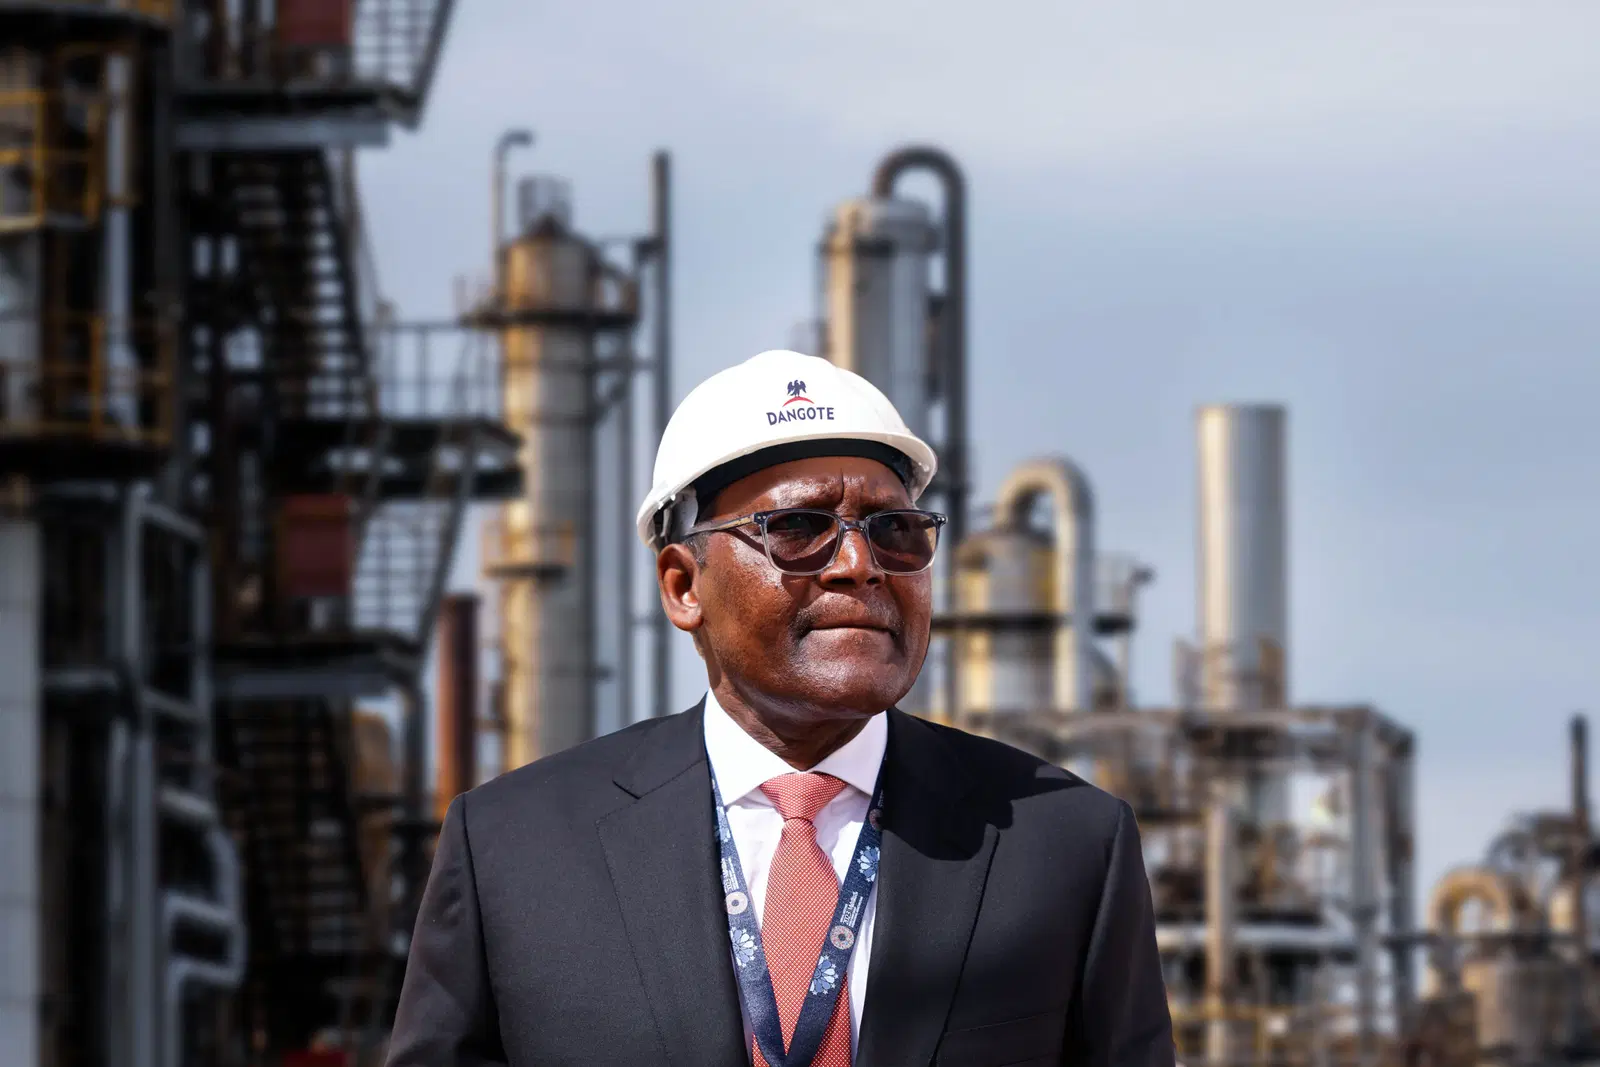
Dangote Group has announced fresh employment opportunities for qualified candidates across several departments at its refinery site.
The vacancies are listed under Dangote-Refinery as the business unit, with the location stated as Dangote Petrochemicals (DPRP) and the department identified as Refinery Site.
The available positions cover procurement, warehouse management, logistics, supply and material planning, compliance, information technology, sustainability and data analytics.
List of Dangote Refinery jobs The 24 positions advertised on the company’s careers platform are:
Industrial Hygienist
Sanitary Inspector
Employee Relations Specialist
Procurement Contract Specialist
Warehouse Team Lead – PPU
Warehouse Manager – PPU
Head, Supply and Material Planning
Head, Logistics & Road Safety Operations
Sales & Operations Planning Manager (S&OP)
Procurement Supplier Specialist
Compliance and Governance Lead
Contract Management Lead
Risk Management Lead (Supply Chain)
Governance and Compliance Specialist
Procurement Supplier Lead
Transport/Dispatch Manager – PPU
Transport/Dispatch Lead – PPU
System Administrative Officer
ESG & Sustainability Manager
ESG / Sustainability Analyst
Lead, System Administration
ISO Management System Coordinator
Data Analytics/System Analyst
Decarbonization Manager
Requirements for Dangote Refinery jobs
The requirements differ depending on the position, and applicants are expected to check the full job description for their preferred vacancy.
Several of the positions require relevant bachelor’s degrees, HNDs or specialised diplomas in fields such as engineering, supply chain management, logistics, business administration, environmental science, public health, information technology and related disciplines.
Some roles also require or favour professional certifications. Depending on the position, these may include certifications in supply chain management, logistics, quality management, information technology and other relevant professional fields.
Work experience is another major requirement, particularly for senior positions.
The experience requested varies from role to role, with some managerial and leadership positions requiring several years of relevant industry experience.
For example, the Warehouse Team Lead – PPU position requires relevant experience in warehouse, logistics or supply chain operations, while the Warehouse Manager – PPU role requires significantly more experience, including managerial exposure.
Applicants for technology-related positions may also need experience with SAP, ERP systems, databases, system administration, Microsoft Excel, Power BI, data analytics and system integration, depending on the vacancy.
For the ISO Management System Coordinator position, candidates are expected to have relevant academic qualifications and experience with international management standards.
The Sanitary Inspector role has more specialised requirements, including qualifications in sanitary inspection, environmental health or public health technology, with related experience preferred.
How to apply for Dangote Refinery jobs Interested candidates should visit the official Dangote careers platform and select the position that matches their qualifications and experience.
Applicants should carefully read the individual job description because the educational qualifications, professional certifications, technical skills and years of experience differ across the 24 positions.
The Nigerian National Petroleum Company Limited (NNPCL) has reduced the pump price of petrol by N5 per litre at its retail outlets in Lagos from N1,360 to N1,355.
Motorists in Lagos and Rivers now pay N1,355 per litre, making them the cheapest locations on NNPC’s updated price list. Abuja buyers are paying N1,370 per litre under the new arrangement.
NNPC petrol prices across Nigeria
Yobe has the highest petrol price at N1,435 per litre, followed by Niger State at N1,433.
Borno, Gombe, Nasarawa and Sokoto are all priced at N1,430 per litre, placing them among the states with the highest fuel prices.
Several south-western states fall within the lower price range. Ogun and Oyo both sit at N1,367, while Osun is priced at N1,358.
Akwa Ibom is at N1,360, just above the Lagos and Rivers rate.
In the south-east, Anambra, Enugu and Imo are each priced at N1,372, with Ebonyi slightly higher at N1,375. Abia is priced at N1,370, the same as Abuja.
Further north, Kaduna is at N1,400, Zamfara at N1,414, while Adamawa, Jigawa, Kebbi, Plateau and Taraba are all priced at N1,420. Bauchi and Kano share a rate of N1,385, while Benue is at N1,410.
In the South-South, Delta is priced at N1,379, Bayelsa and Edo at N1,380, and Cross River at N1,390. Kwara is at N1,375, while Kogi is priced at N1,390. The full breakdown of the new NNPC petrol prices per litre is as follows:
Lagos: N1,355 Rivers: N1,355 Akwa Ibom: N1,360 Osun: N1,358 Ogun: N1,367 Oyo: N1,367 Abia: N1,370 Abuja: N1,370 Anambra: N1,372 Enugu: N1,372 Imo: N1,372 Ebonyi: N1,375 Kwara: N1,375 Ekiti: N1,377 Ondo: N1,377 Delta: N1,379 Bayelsa: N1,380 Edo: N1,380 Bauchi: N1,385 Kano: N1,385 Cross River: N1,390; Kogi: N1,390 Kaduna: N1,400 Benue: N1,410 Zamfara: N1,414 Adamawa: N1,420 Jigawa: N1,420 Kebbi: N1,420 Plateau: N1,420 Taraba: N1,420 Borno: N1,430 Gombe: N1,430 Nasarawa: N1,430 Sokoto: N1,430 Niger: N1,433 Yobe: N1,435

Judgement On ADC Will Lead To Your Downfall – US Firm Warns Tinubu

NDC Raises Alarm Over Fresh Restrictions In Abuja, Fingers APC


